How To Use Financial Ratios In Credit Analysis
About This Course
Ratio analysis helps lenders and analysts to evaluate a borrower’s operating performance (profitability and productivity) and financial condition (liquidity, leverage, solvency) in order to assess a borrower’s ability to repay its obligations.
This program focuses on well-known and reliable ratios to assist in identifying financial trends and evaluating analytical strengths and weaknesses of borrower impacting its ability to repay.
This session will explain how to employ ratios to measure and evaluate a borrower’s performance and financial condition. Borrower’s financial profile does change over its life cycle as it moves from new entity to mature firm, and this change over time will be explained and illustrated so that participants will see link between positive cash flows and good operating performance and financial condition.
Topics covered in this session:
- Financial Condition
- Liquidity
- Current and Quick Ratios to evaluate short-term liquidity
- Working Capital Analysis, i.e., cash cycle, days receivable, days inventory, days payable
- Fixed assets/ net worth
- Leverage
- Various ratios to measure the proportion of support provided by owners and creditors- i.e., debt/ worth ratio, short-term debt/ total debt, long-term debt/ total debt
- Solvency
- Measures for determining the ability of the firm to simultaneously satisfy the expectations of lenders and owners while maintaining the earning assets of the firm, i.e., interest coverage ratio, cash flow/ current maturities of long-term debt, sustainable growth rate
- Liquidity
- Operating Performance
- Profitability
- To measure the ability of management to utilize their assets to generate sales and maximize profits, i.e., profit/ sales, profit/ equity, profit/ total assets
- Performance ratios to measure the relationship between sales, costs and expenses and how their changes affect the bottom line
- Repayment Ability
- To estimate repayment ability from cash flow, i.e., global debt service coverage ratio
- Profitability
Learning Objectives
After attending this presentation, participants will be able to….
- Define financial condition, operating performance, and repayment ability
- Describe use of ratios in credit analysis
- Explain how credit analysis is employed to determine repayment ability
- Recognize appropriate ratio values in assessing financial condition, operating performance, and repayment ability
Who Should Attend:
Beginning Professionals in the Banking, Credit and Financial Services Industry, e.g., credit analysts; business bankers; commercial lenders; and support staffers in loan accounting, loan operations, loan documentation, loan closers
*This program does NOT qualify, nor meet the National Standard for NASBA accreditation.
Your Instructor
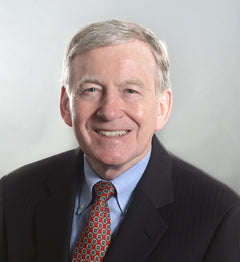
A frequent speaker, instructor, advisor and writer on credit risk and commercial banking topics and issues, Martin J. "Dev" Strischek is principal of Devon Risk Advisory Group based near Atlanta, Georgia. Dev advises, trains, and develops for financial organizations risk management solutions and recommendations on a range of issues and topics, e.g., credit risk management, credit culture, credit policy, credit and lending training, etc. Dev is the former SVP and senior credit policy officer at SunTrust Bank, Atlanta. He was responsible for developing, implementing, and administering credit policies for SunTrust’s wholesale lines of business--commercial, commercial real estate, corporate investment banking, capital markets, business banking and private wealth management. Prior to SunTrust, Mr. Strischek was chief credit officer for Barnett Bank’s Palm Beach market. Dev is also a member of the Financial Accounting Standards Board’s (FASB’s) Private Company Council (PCC).
This course is covered under team memberships.
See Team Memberships