Asset Based Lending: Policy and Underwriting Guidance for Borrowing Base Lending on Receivables and Inventory
About This Course
Asset-based lending (often referred to as “ABL”) is a form of commercial lending designed to finance safely the working capital needs of a borrower whose cash flow currently may not support debt repayment. Like other commercial loans, cash flow is the primary repayment source for an asset-based loan but with stronger reliance on the company's assets as collateral and firmer control over the receipts of the collateral’s liquidation.
Collateral typically available to secure the asset-based loan includes accounts receivable, inventory, machinery and equipment, general and specific intangibles, real estate, and other assets. Because working capital support is the primary objective of most asset-based loan facilities, accounts receivable and inventory generally are the bank's core collateral. Personal guaranties, often secured, can be taken.
Monitoring and controlling collateral is critical to the asset-based lender to mitigate repayment risk. Collateral evaluation begins with a comprehensive field examination to determine value, followed by a continuing program of periodic examinations. The collateral and loan values are monitored continuously (daily/weekly/monthly) to ensure that the realizable value of the collateral is always sufficient to repay outstandings.
Topics covered in this session
· Characteristics of ABL borrowers
- Rapid sales growth
- Negative operating cash flow
- "Evergreen” lending
Customers’ advantages for an ABL facility vs factoring
Collateral considerations
- Receivables eligibility
- Inventory eligibility
Credit risk mitigation
- Lock boxes
- Audits
- Borrowing base certificate
Types of facilities
- Lines of credit
- Longer-term revolving facilities
How advance rates are determined
- Frequency of funding
- Financial condition and operating performance
- Cost of funds
Who Should Attend:
- Credit Analysts
- Credit Managers
- Loan review officers
- Work-out officers
- Commercial lenders
- ABL officers and managers
- Credit Risk Managers
- Chief Credit Officers
- Senior Lenders
- Senior Lending Officer
- Bank Director
- Chief Executive Officer
- President
*This program does NOT qualify, nor meet the National Standard for NASBA accreditation.
Your Instructor
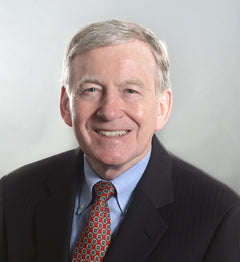
A frequent speaker, instructor, advisor and writer on credit risk and commercial banking topics and issues, Martin J. "Dev" Strischek is principal of Devon Risk Advisory Group based near Atlanta, Georgia. Dev advises, trains, and develops for financial organizations risk management solutions and recommendations on a range of issues and topics, e.g., credit risk management, credit culture, credit policy, credit and lending training, etc. Dev is the former SVP and senior credit policy officer at SunTrust Bank, Atlanta. He was responsible for developing, implementing, and administering credit policies for SunTrust’s wholesale lines of business--commercial, commercial real estate, corporate investment banking, capital markets, business banking and private wealth management. Prior to SunTrust, Mr. Strischek was chief credit officer for Barnett Bank’s Palm Beach market. Dev is also a member of the Financial Accounting Standards Board’s (FASB’s) Private Company Council (PCC).
This course is covered under team memberships.
See Team Memberships