GAAP - Update on New Accounting Principles and Impacts on Borrowers' Financials
About This Course
We tend to take accounting for granted—debits equal credits, total assets equal total liabilities and stockholder’s equity. Generally accepted accounting principles (GAAP) are generally accepted because they are generally written for the ages, so they do not change often, but when they do, there are good reasons for the change.
Good reasons for updating as business and the economy do change over time, and several new principles warrant review to understand how they will affect both borrowers and lenders, specifically, new GAAP for revenue recognition, lease capitalization, current expected credit losses (CECL) as well as changes to not-for-profit organizations’ financials.
Much of the change in GAAP in recent years is the result of collaboration between the Financial Accounting Standards Board (FASB) and the International Accounting Standards Board (IASB) to bring US and international accounting principles closer together. At some point, both groups decided they were as close as they would be likely to get on several key concepts—revenue recognition, lease capitalization, and CECL. In addition, FASB decided to revise financial statement disclosure for the large and growing not-for-profit segment of the American economy.
This Course Covers: This accounting webinar will explain these new concepts and how they affect borrowers and how lenders should incorporate these changes into their own analyses and underwriting of borrowers:
-
Background of FASB and IASB accounting convergence
- Close, but no cigar
- Differences still exist
-
Revenue recognition
- Seller recognizes revenue when buyer gets possession of good or service
- Generally sooner than later
- More emphasis on gross revenues, less netting revenues against expenses
-
Lease capitalization
- Troublesome off-balance-sheet loophole finally plugged
- Whether operating or financing lease, both are capitalized
- Both lease liability and right of use (ROU) asset put on balance sheet
- Higher leverage ratios, lower return on asset ratios
- Cash flow impacts
-
CECL
- Incurred loss replaced by loss over life of loan, so banks with large mortgage and consumer loans will have higher CECLs
- Higher probability of default the smaller the borrower and the longer the term
- CECL means higher provision for credit losses in financials of borrowers, not just bankers
-
Not-for-profits
- Balance sheet simplified
- More disclosure of liquidity
*This program does NOT qualify, nor meet the National Standard for NASBA accreditation.
Your Instructor
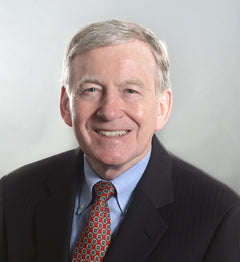
A frequent speaker, instructor, advisor and writer on credit risk and commercial banking topics and issues, Martin J. "Dev" Strischek is principal of Devon Risk Advisory Group based near Atlanta, Georgia. Dev advises, trains, and develops for financial organizations risk management solutions and recommendations on a range of issues and topics, e.g., credit risk management, credit culture, credit policy, credit and lending training, etc. Dev is the former SVP and senior credit policy officer at SunTrust Bank, Atlanta. He was responsible for developing, implementing, and administering credit policies for SunTrust’s wholesale lines of business--commercial, commercial real estate, corporate investment banking, capital markets, business banking and private wealth management. Prior to SunTrust, Mr. Strischek was chief credit officer for Barnett Bank’s Palm Beach market. Dev is also a member of the Financial Accounting Standards Board’s (FASB’s) Private Company Council (PCC).
This course is covered under team memberships.
See Team Memberships