Deposit Compliance Series: Regs D/DD
About This Course
Reg DD is firmly a consumer-protection regulation. There are specific descriptions that must be provided, from the Annual Percentage Yield (APY), to fees and penalties, to any other feature that an account may have. At any time, if a financial institution doesn’t truthfully describe what can, will, or has happened, consumer harm can occur. We don’t want that. Not only is it bad for business, but it carries regulatory consequences! Congress never could have imagined the changes to technology (online banking) or society (social media) and the impact they would have on banking. The rules still remain, whether an account is being advertised on an old-fashioned rate board or a tweet. Do you know how to get it all right? On the other hand, Reg D and the Federal Reserve Act is all about setting aside appropriate reserves in case there is a run on the bank. If there is a panic, and masses of people flood the institution to take their money out, your institution must have enough liquid funds to service those demands. Financial institutions are not allowed to invest or lend out 100% of the money they have on deposit. No, there are particular rules that require different types of deposits be held in reserve and just sit there. Reg D is firmly a Safety and Soundness regulation. Even though it is not a consumer protection regulation, there are components that require the understanding and attention of a compliance officer. There are eligibility requirements and both mandatory and optional withdrawal limitations. Do you know how to get it all right?
Topics covered in this course
- Required advertising disclosures
- Triggering terms
- What can (and cannot) be different for ads in different mediums, including online advertising
- 100% understanding (and calculation!) of the APY
- General disclosure requirements
- Who must get them
- When they must be provided
- Account opening disclosure requirements
- Deposit accounts
- Time accounts
- Eligibility requirements
- Withdrawal limitations
- Special disclosures for overdraft services
- Change in Terms disclosure requirements
- Periodic Statement requirements
- Record retention
- UDAP traps
Interested in more Deposit Compliance topics? Check out our other courses on Reg E and Reg CC!
Your Instructor
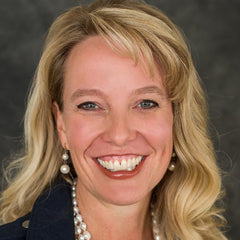
Rebekah is the owner of Elucidate LLC, a compliance training and consulting company. Elucidate means to "make clear, explain, throw light upon", and describes Rebekah's desire to illuminate the complexities of compliance with passion and fun. She's created and produced a TRID music video parody and several Compliance Breakout escape rooms, which she frequently provides at state banking compliance conferences. She is an accomplished speaker and regularly provides webinars through BOL and Compliance Resource. Rebekah is currently serving as the VP Director of Compliance for a $6 Billion community bank in Montana. She began her career in 1995 at a private lending company, but soon settled into banking, where she's covered nearly all of it - customer service and teller work, loan processing and review, and security and business continuity. She now oversees CRA, BSA and all aspects of compliance as a senior leader. She has successfully navigated numerous FDIC Compliance, CRA, and BSA Exams. Rebekah has a bachelor's degree in Organizational Leadership from Chapman University (Magna cum Laude), attended the American Bankers Association National Compliance School in 2003, and has held her Certified Regulatory Compliance Manager designation since 2006.
CPE & Accreditation
This course qualifies for 3.2 CPE/ NASBA. Your certificate and transcript are available immediately upon completion.
View accreditation details Hide accreditation details
CPE/NASBA - QAS Self Study
Noggin Guru, Inc. dba Lorman Education Services and BankersHub is registered with the National Association of State Boards of Accountancy (NASBA) as a sponsor of continuing professional education on the National Registry of CPE Sponsors. State boards of accountancy have final authority on the acceptance of individual courses for CPE credit. Complaints regarding registered sponsors may be submitted to the National Registry of CPE Sponsors through its website: www.nasbaregistry.org.
For more information regarding administrative policies such as complaint and refund, please contact our offices at 866-352-9539.
Please note: You must attend at least 50 minutes to obtain credit. Final CPE approval belongs with each state's regulatory board. Credit is based on a 50-minute credit hour.
For more detailed information about the course, including the outline, content, and objectives, please refer to the 'Description' tab on this webpage.
Field Of Study: Specialized Knowledge
Prerequisite: Basic knowledge of the banking industry, business, or law
Level of Knowledge: Intermediate
Advanced Preparation: None
Delivery Method: QAS Self Study
Requesting CE:
Upon completion of this course, please email
creditrequest@nogginguru.com
to obtain a CE certificate.
This course is covered under team memberships.
See Team Memberships